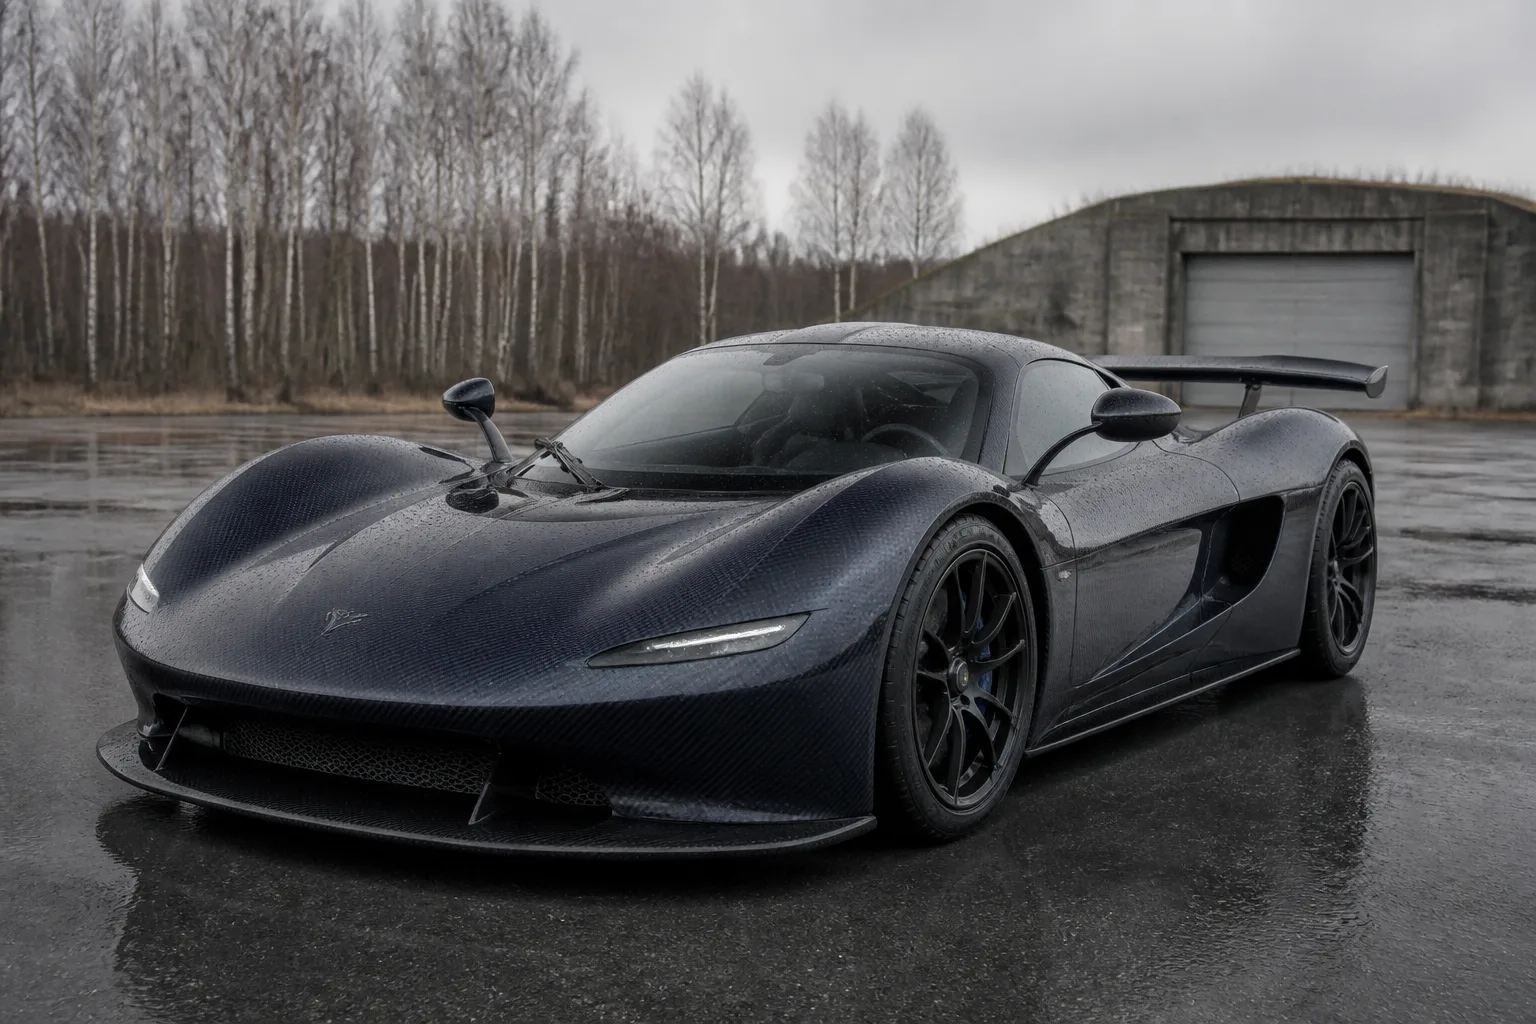
Koenigsegg finance, priced against the car and not a book value.
Not the dealers, not the trade guides, and not us. Three of the five cars advertised in Britain this month carry no price at all. So a Koenigsegg is not funded off a rate card or a book figure. It is funded against a valuation of the specific car, agreed before you apply. We arrange that for limited companies and for individuals, with no minimum advance.
- Cars in the rarest run here
- 6
- UK cars advertised, 8 August 2026
- 5
- Of those, with a published price
- 2
What a Koenigsegg is worth, and why no one publishes it
On 8 August 2026 there were 5 Koenigseggs publicly advertised for sale in the United Kingdom. 3 of them carried no price at all, including two Regeras at the official UK dealer. Only 2 showed a figure: a 2025 Jesko at £4,260,000 including VAT with 2,500 miles, and a 2022 Regera at £2,600,000.
That is worth stating plainly because of what it means for the finance. There is no trade guide to look a Koenigsegg up in and no going rate to lend against. A lender cannot price what the market has not published, so the advance follows a valuation of the specific car, and the paperwork behind that car does more work than the model name does.
Asking prices as published by the seller. They are not transaction prices and they are not a valuation, and we would not present them as either.
What Koenigsegg finance costs a month
Every figure assumes you put down 20 per cent and pay over 48 months at 8.9 per cent. The last column shows the effect of pushing 40 per cent of the price into a single payment at the end rather than paying it off as you go. These are estimates rather than quotes, and nobody has looked at your circumstances yet.
| Model | Built | Price | Paying it off | With a payment at the end |
|---|---|---|---|---|
| Gemera | 300 | £1,800,000 | £35,766 | £23,223 |
| Jesko | 125 | £3,000,000 | £59,610 | £38,705 |
| CC850 | 70 | £3,650,000 | £72,526 | £47,091 |
A used Koenigsegg is not necessarily cheaper to finance than a new one. On an Agera RS or a One:1 the market has moved above what the car cost, which is the opposite of how the rest of the car world behaves and the reason a refinance against one is worth asking about.
Types of Koenigsegg finance
Supercar finance at this level is not a product you pick off a shelf. These are the four shapes a deal takes, and which one is available depends more on the car than on you. The full detail is on the finance options page.
-
Hire purchase on a Koenigsegg
The whole cost across the term and the car is yours at the end. Nothing is deferred, so nobody has to forecast a value four years out. On Koenigsegg cars that matters more than it does anywhere else, and it is why most hire purchase deals we place on this marque go through without argument. The deposit is the main variable.
-
Lease purchase on a Koenigsegg
Part of the balance is left to one payment at the end. The monthly car finance figure falls and the debt does not. Lease purchase is offered on these cars less freely than on an ordinary supercar, because the lender is committing to a closing figure on a run of twenty five rather than twenty five thousand.
-
Personal contract purchase on a Koenigsegg
The lender promises the closing figure rather than estimating it, and charges for carrying that risk. Hardest of the four to obtain here. A broker offering a PCP freely on a Koenigsegg Regera is describing lease purchase and calling it something else.
-
Refinancing a Koenigsegg you already own
Capital released against a car already owned, with the deposit question removed entirely. This does the most work on this marque, because several of these cars are worth more now than they cost.
The Koenigsegg finance process
Koenigsegg finance is a specialist asset-backed loan secured against the car itself. Four steps, and the first one is short.
-
We establish whether there is a deal
What the car is, what you are paying, how you want it owned, and what sits behind the application. That conversation happens before anything touches your credit file, and it is where we tell you if the answer is no.
-
We approach the lenders whose appetite fits
Not all of them. A credit file full of searches is worth less than a clean one, and the lenders who write hire purchase on a Koenigsegg are not always the ones who will consider a refinance against one.
-
You see the terms in writing
The rate, the deposit, the total cost across the term and the early settlement position, set out rather than buried. Two agreements at the same monthly figure are routinely thousands apart once those are in view.
-
Nothing is submitted until you say so
No lender sees the case and no search is run until you have seen the numbers and told us to proceed.
Koenigsegg finance FAQs
- How much is a deposit on a Koenigsegg?
- There is no published figure and anyone quoting one has invented it. Between 20 and 40 per cent is the usual starting point on a car at this value, and the worked example on this page assumes 20 per cent. What actually moves it is the car and the borrower rather than a rate card: a lender advancing against a car with a documented run of seven wants more equity in the deal than one advancing against a car with a run of three hundred.
- Can a normal person buy a Koenigsegg?
- Not on ordinary terms, and it is worth being straight about that. The cheapest Koenigsegg publicly advertised in the UK when we last checked was a 2022 Regera at £2.6 million. Finance changes how that is paid for and over what period, and it does not change what the car costs. What it does do is stop the purchase requiring the whole sum in cash on the day.
- Can you finance a Koenigsegg in the UK?
- Yes, through specialist lenders rather than through a high street bank or a manufacturer scheme, because no Koenigsegg captive finance arm exists in this market. Hire purchase, lease purchase, personal contract purchase and a refinance against a car already owned all apply. We arrange it for limited companies and for individuals, with no minimum advance.
- What is a Koenigsegg worth?
- There is no book value, and that is a fact about the market rather than a gap in our data. Of the five Koenigseggs publicly advertised for sale in the UK on 8 August 2026, three carried no price at all, including two Regeras at the official UK dealer. The two that did were a 2025 Jesko at £4.26 million including VAT and a 2022 Regera at £2.6 million. Every deal is therefore worked from a valuation agreed at the outset.
- Is a Koenigsegg a good asset to borrow against?
- Lenders think so more often than the volumes would suggest, because the runs are small and documented. Seven One:1s exist. Fourteen CCRs. Six CC8Ss. Scarcity that specific is easier to underwrite than a car built in the tens of thousands, where the lender is exposed to a market that can move against it. The condition and the history of the individual car carry more weight than the model does.
- How long can a Koenigsegg be financed over?
- Twelve to sixty months is the normal range and forty eight is the most common, which is the term every figure on this site assumes. A longer term lowers the monthly payments and raises the total cost. On a car this rare a lender will sometimes want a shorter one, because it is less comfortable taking a view on a value further out.
- Can a limited company buy a Koenigsegg on finance?
- Yes, and it is a large share of what we arrange. The agreement is written in the company name, the lender underwrites the company rather than only the individual, and directors guarantees are common. How the car is treated for tax, and the benefit in kind position if it is available for private use, are questions for your accountant and we will not pretend to answer them.
- What is the 50 per cent rule on car finance?
- It is a Consumer Credit Act right, called voluntary termination, and it does not attach to an unregulated business agreement, only to a regulated consumer one. Under a regulated agreement it lets a borrower hand the car back once half the total amount payable has been paid. Which type you sign decides whether the right is there at all, so ask us if it matters to you.
- Are you regulated by the Financial Conduct Authority?
- We are not authorised or regulated by the FCA ourselves, and we do not hold ourselves out as being. Finance taken wholly or predominantly for business purposes sits outside the consumer credit regime and we arrange that directly. Where an agreement is regulated consumer credit, it is arranged through an FCA authorised broker partner, and that firm is responsible for the regulated activity and for any advice given on it. You can confirm that for yourself on the FCA Register.
- Are you connected to Koenigsegg?
- No. We have no affiliation with Koenigsegg Automotive AB. We are not a Koenigsegg dealer and not an authorised representative of the manufacturer. We are an independent finance company arranging lending against these cars, and we use the name only to describe what we do.
Talk to us about Koenigsegg finance
We come back with which agreements the car supports and what each one is likely to cost. If none of them work, that is the answer you get.